In this guide
- What is a credit enquiry?
- Soft enquiry: checks that do not affect your score
- Hard enquiry: checks that can lower your score
- Soft vs hard enquiry at a glance
- Why many hard enquiries worry lenders
- How long do enquiries stay on your report?
- Smart ways to check and apply without hurting your score
- Checklist before your next loan application
- Frequently asked questions
- Planning to apply for a loan?
Updated: 8 November 2026
Many people want to check their CIBIL score before applying for a loan, but stop because they have heard that "checking the score reduces it". Others apply to several lenders in one week and are surprised when their score drops. Both situations come from the same confusion: the difference between a soft enquiry and a hard enquiry. This guide explains, in plain words, which checks affect your score, which do not, and how to plan your loan applications so that enquiries do not hurt your chances.
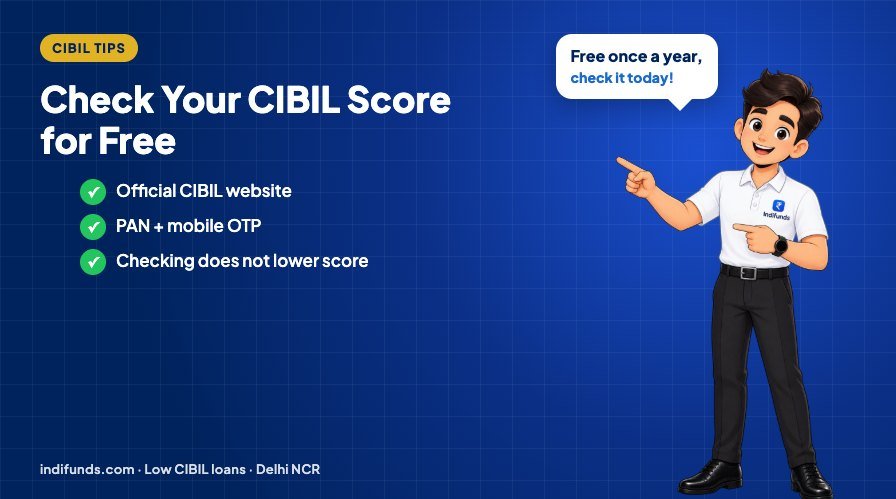
Quick answer: No, checking your own CIBIL score does not lower it. When you check your own score, it is recorded as a soft enquiry, which lenders do not treat as a sign of credit hunger. Your score can be affected when a lender checks your report because you applied for a loan or credit card. That is a hard enquiry. One hard enquiry has a small effect, but many hard enquiries in a short time can make lenders cautious.
What is a credit enquiry?
Every time someone looks at your credit report, the credit bureau keeps a record of it. This record is called an enquiry. India has four credit bureaus licensed by the Reserve Bank of India (RBI): TransUnion CIBIL, Experian, Equifax and CRIF High Mark. Each of them keeps your loan and credit card history and gives you a score, usually between 300 and 900.
Enquiries are listed in a separate section of your credit report. They show who checked your report and when. What matters is why the report was checked. That decides whether the enquiry is soft or hard.
Soft enquiry: checks that do not affect your score
A soft enquiry happens when your report is checked for a reason that is not a fresh credit application. Common examples are:
- You check your own CIBIL score on the bureau's website or through a trusted app.
- Your existing bank or card company reviews your account from time to time.
- A lender checks your profile to send you a pre-screened offer that you did not ask for.
Soft enquiries are generally not visible to lenders in the same way and do not count against you. You can check your own score as often as you like. In fact, checking it regularly is a good habit, because it helps you spot mistakes and fraud early. Our step-by-step guide on how to check your CIBIL score for free shows you how to do it.
Hard enquiry: checks that can lower your score
A hard enquiry happens when a bank or NBFC checks your report because you applied for credit. For example:
- You fill in an application for a personal loan, home loan, car loan or two-wheeler loan.
- You apply for a new credit card or a credit limit increase.
- You apply for a "buy now, pay later" limit or an app-based loan that pulls your report.
Each hard enquiry stays on your credit report and is visible to other lenders. A single hard enquiry usually has only a small and temporary effect. The real problem starts when several hard enquiries appear close together.
Soft vs hard enquiry at a glance
| Point | Soft enquiry | Hard enquiry |
|---|---|---|
| Who starts it | You (own check), or your existing lender for a review | A lender, after you apply for credit |
| Typical reason | Checking your own score, account review, pre-screened offer | Loan or credit card application |
| Effect on score | None | Small drop possible; bigger concern if many in a short time |
| Seen by other lenders | Not counted against you | Yes, listed in the enquiry section |
| Your consent | Your own check needs your OTP / login | Given when you sign or submit the application |
| How often is it okay | As often as you like | Only when you are ready to apply |
Why many hard enquiries worry lenders
When a lender sees five or six loan applications in a few weeks, it may read this as a sign that you urgently need money or that other lenders have already said no. This is sometimes called being "credit hungry". Even if your income is stable, many recent enquiries can lead to a lower score and to more rejections, and each rejection often comes after one more hard enquiry. This cycle is common among borrowers who already have a low score.
If you have been rejected recently, read what to do after a loan rejection before you apply again.
How long do enquiries stay on your report?
Enquiries remain listed in your credit report for a period of time, and lenders give the most weight to recent ones, typically those from the last few months. As time passes without new applications, older enquiries matter less. The exact way each bureau's scoring model treats enquiries is not public, so be careful with anyone who promises a specific number of points or a fixed time for your score to "recover".
Smart ways to check and apply without hurting your score
1. Check your own report first
Before you apply anywhere, download your report and read it line by line. Look at overdue accounts, DPD (days past due) entries and any loan you do not recognise. Our guide on how to read your CIBIL report explains terms like DPD, "settled" and "written off".
2. Fix errors before you apply
If you find a wrong entry, raise a dispute with the credit bureau and the lender. Applying while an error is still on your report only adds hard enquiries without improving your chances.
3. Know the minimum score lenders look for
Different lenders have different cut-offs. Read the minimum CIBIL score for a personal loan to understand where you stand and what options exist if your score is lower.
4. Do not apply to many lenders at once
Filling in loan forms on many apps and websites in one day is the fastest way to collect hard enquiries. Shortlist one or two suitable options and apply only there.
5. Ask how the lender checks your profile
Before you share your PAN or sign a form, it is fair to ask whether a full credit report will be pulled at that stage. A genuine lender or loan advisor will explain the process.
6. Space out applications
If one application is rejected, find out why and work on that reason first, rather than applying again the next day.
Checklist before your next loan application
- I have checked my own CIBIL score (soft enquiry, no effect on score).
- I have read my full report and there are no errors or unknown accounts.
- I know how many hard enquiries I have had in the last few months.
- My current EMIs leave enough room in my monthly salary for a new EMI.
- I have shortlisted one or two options instead of applying everywhere.
- I will never pay any fee to a person or account before my loan is approved.
For more ways to improve your profile, see our tips on how to increase personal loan approval chances with a low CIBIL score.
Frequently asked questions
Does checking my own CIBIL score reduce it?
No. Checking your own score is a soft enquiry and does not affect it. You can check it as often as you want.
How much does one hard enquiry reduce my CIBIL score?
The bureaus do not publish an exact number. A single hard enquiry usually has a small, temporary effect. Several hard enquiries in a short period are a bigger concern for lenders than any one enquiry.
Is checking my score on a loan app a soft or hard enquiry?
If the app only shows you your own score, it is normally a soft enquiry. If you submit a loan application on that app, the lender may make a hard enquiry. Read the consent text before you tap "submit".
Can I remove hard enquiries from my CIBIL report?
A genuine hard enquiry made after your own application cannot be removed. If you see an enquiry from a lender you never applied to, raise a dispute with the credit bureau, as it could be an error or a sign of misuse of your details.
Do lenders see the soft enquiries on my report?
Soft enquiries, such as checking your own score, are not treated as credit applications and do not count against you in a lender's decision.
Will a loan rejection lower my CIBIL score?
The rejection itself is not reported to the bureau. What can affect your score is the hard enquiry made when you applied. That is why applying again and again after rejections can make things worse.
Planning to apply for a loan?
Indifunds is based in Noida and helps salaried people in Delhi NCR understand their loan options, including borrowers with a low CIBIL score. Instead of applying on many apps and collecting hard enquiries, you can talk to our team first about which option suits your profile. We do not charge any fee before approval. Check your eligibility or call our support team on 8595702470.
*This article is for general information only and is not financial advice. Loan approval, amount, interest rate and tenure are subject to eligibility criteria, verification and the lender's final approval. All terms and charges are governed by the loan documents.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.