In this guide
Has your personal loan been rejected by a bank or an app? A loan rejection feels personal, but it is usually about one or two specific things in your profile. The good news: most of them can be fixed, and a rejection today does not mean you cannot borrow in a few months.
Quick answer: Don't apply again straight away. First find out why you were rejected, check your credit report for mistakes, reduce your existing EMIs if you can, and then apply with one lender whose criteria actually match your profile.
Step 1: Find out the real reason
Lenders are expected to tell you the main reason your application was rejected. If they did not, ask the branch or the loan officer to share it in writing or by email. Without the reason, you are guessing.
The most common reasons are:
| Reason | What it usually means |
|---|---|
| Low CIBIL score | Late EMIs, a default, a settled account or very high credit card usage in the past. |
| Too many existing EMIs | Your current EMIs already take a large part of your salary, so a new EMI looks risky. |
| Income below their minimum | Each lender has a minimum salary. Banks often set it higher than NBFCs. |
| Too many recent applications | Several loan enquiries in a few weeks make you look desperate for credit. |
| Job or company profile | New job, probation period, or a company not on the lender's approved list. |
| Documents or address issues | Name mismatch between PAN and Aadhaar, missing salary slips, or an area the lender does not serve. |
Step 2: Check your credit report (it's free)
You are entitled to one free full credit report every year from each credit bureau, including CIBIL. Download yours and look at it line by line:
- Loans or cards you never took.
- A loan you closed that still shows as "active".
- Late payments that you actually paid on time.
- Your name, PAN or date of birth spelled wrongly.
If you find a mistake, raise a dispute on the bureau's website. Bureaus have to resolve disputes within a fixed time (about 30 days), and correcting even one wrong entry can lift your score.
If the report is correct but the score is low, read our guide on how to improve your CIBIL score after a default.
Step 3: Stop applying everywhere
This is the most common mistake. After one rejection, many people apply to five apps and three banks in the same week. Every application is recorded as an enquiry on your credit report, and a cluster of enquiries pulls the score down further. The next lender then sees both the low score and the panic.
Give yourself a gap. If the reason was a low score or too many enquiries, wait at least 2–3 months before the next application, and use that time to fix the cause.
Step 4: Fix what you can before the next application
If your existing EMIs are too high
Many lenders want your total EMIs (old plus new) to stay within roughly 40–50% of your take-home salary. Close a small loan, pay down a credit card, or ask for a smaller amount or a longer tenure. Use the EMI calculator to find an EMI you can comfortably pay.
If you have overdue amounts
Clear them, or at least bring them current. If you settle an account, keep the settlement and closure letters safe. Understand the difference first: loan settlement vs loan default.
If your credit card usage is high
Try to keep each card's balance well below its limit. High usage month after month is read as stress.
If your documents had a problem
Get your PAN and Aadhaar details to match, keep your latest salary slips ready and make sure your salary is credited to your bank account.
Step 5: Choose a lender that matches your profile
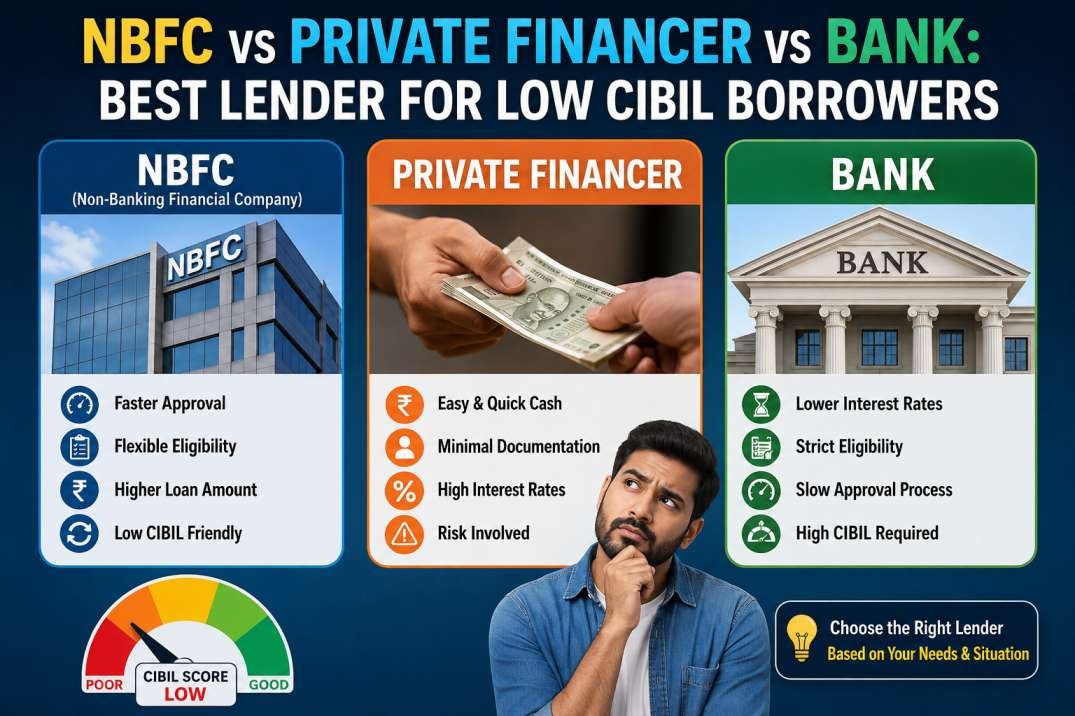
Banks mostly lend to people with good scores and long, clean credit histories. If your score is low or you have a past default, applying to another big bank will often end the same way.
NBFCs and private lending partners may look more at your current salary, job stability and repayment capacity. Read the comparison: NBFC vs private financer vs bank for low CIBIL borrowers.
A guarantor or co-applicant with a steady income can also make a big difference to approval.
Step 6: Watch out for loan fraud after a rejection
People who have just been rejected are the main target of fake loan offers. Be careful if anyone:
- Asks for a "file charge", "processing fee" or "insurance" before your loan is approved in writing.
- Promises "100% approval" without seeing your documents.
- Asks for your OTP, UPI PIN or net banking password.
- Contacts you only on WhatsApp and has no office address.
A genuine lender never needs your OTP or password.
When can you apply again?
| If you were rejected because of… | Apply again after |
|---|---|
| A mistake in your credit report | The bureau confirms the correction |
| Too many recent enquiries | 2–3 months without new applications |
| High existing EMIs | You close or reduce one of them |
| Low CIBIL score | A few months of on-time payments, or apply to a lender that assesses salary |
| Income below the minimum | A salary increase, or a lender with a lower minimum |
| Documents | As soon as the documents are corrected |
Rejected by a bank? How Indifunds can help
Indifunds works with salaried people in Delhi NCR who have a low CIBIL score or a past rejection. Our team looks at your current salary and repayment capacity, not just the score.
- Salaried, with salary credited to your bank account
- Monthly salary of ₹35,000 or more
- Living in Delhi, Noida, Greater Noida, Gurugram, Ghaziabad or Faridabad
Documents usually needed: Aadhaar, PAN, latest salary slip or offer letter, and 3 months' bank statement. In some cases, for example if you live in a rented house, a guarantor may be needed. Final approval and terms depend on the lending partner's verification.
Check your eligibility. It takes about a minute.
Frequently asked questions
Loan reject hone ke baad dobara kab apply karna chahiye?
Fix the reason first. In most cases, wait 2–3 months without new applications, then apply with one lender whose criteria match your profile.
Does a loan rejection reduce my CIBIL score?
The rejection itself is not shown on your report, but every application creates an enquiry. Many enquiries in a short time can lower your score.
Bank ne loan reject kar diya, ab kahan apply karein?
If the reason was your credit history, an NBFC or private lending partner that assesses your salary may be a better fit than another bank. A secured loan (against a car or property) is another option.
Can I ask the bank why my loan was rejected?
Yes. Lenders are expected to share the main reason for rejection. Ask for it in writing or by email.
Will paying a fee guarantee loan approval?
No. Never pay any amount before your loan is approved in writing. Anyone asking for an upfront fee to "guarantee" approval is a warning sign.
Can I get a loan with a 600 CIBIL score after a rejection?
It is possible with lenders that look at salary and repayment capacity, though terms may be stricter. See minimum CIBIL score for a personal loan.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.