In this guide
If your CIBIL score is low, where you apply matters as much as what you apply for. Banks, NBFCs and private lending partners each have different rules, costs and speed. This comparison helps you decide which type of lender fits your score and situation, so you avoid unnecessary rejections and high-cost loans.
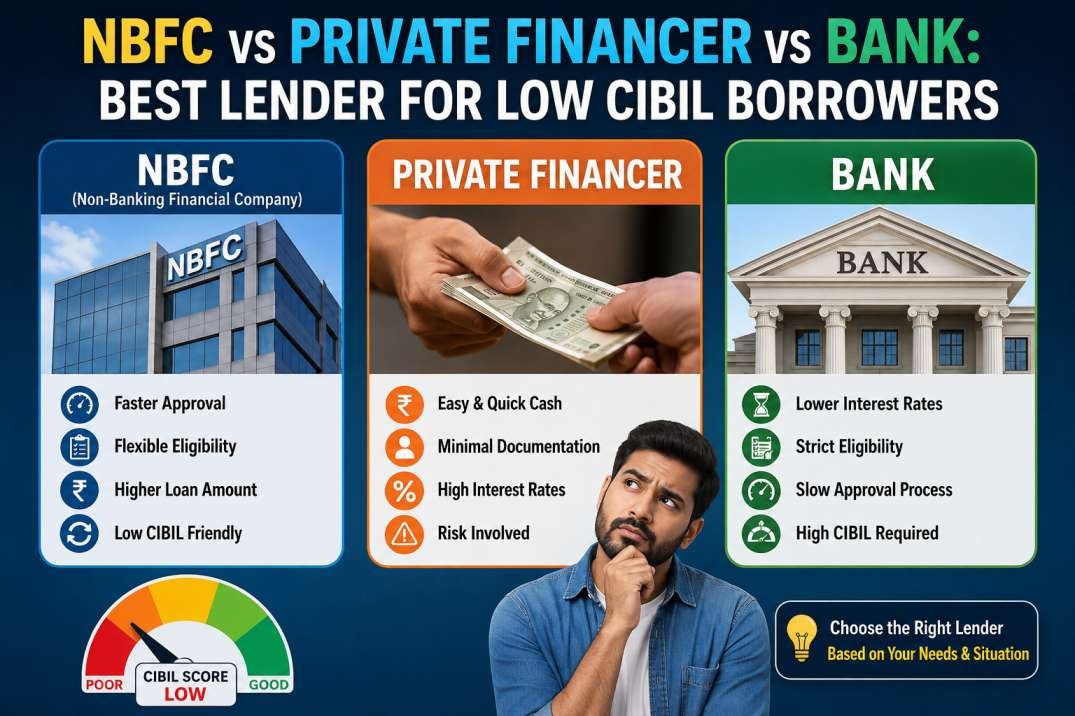
Quick answer: Banks offer the lowest rates but usually need a CIBIL score of 700 to 750 or more. NBFCs are more flexible, often considering scores around 650 and above, at higher rates. Private lending partners assess low-score and past-default applicants case by case, focusing on salary and repayment capacity, at the highest cost of the three. Choose the lowest-cost lender you genuinely qualify for.
Bank vs NBFC vs private lending partner at a glance
| Factor | Bank | NBFC | Private lending partner |
|---|---|---|---|
| Typical CIBIL expectation | 700 to 750+ | About 650+ | No fixed cut-off; case by case |
| Interest cost | Lowest | Moderate | Highest |
| Decision style | Mostly automated rules | Rules plus some review | Manual review of your full profile |
| Documents | Detailed | Moderate | Basic KYC, salary slips, bank statement |
| Loan amount | Higher | Medium to high | Usually smaller |
| Best for | Good credit profiles | Fair profiles | Low score or past default with stable salary |
Banks: lowest cost, strictest rules
Pros: the lowest interest rates, higher loan amounts and long tenures.
Cons: strict score cut-offs, approved-employer lists and automated decisions. A recent default almost always leads to rejection, and each application adds a hard enquiry.
Apply here if: your score is 700 or above and you have no recent missed payments.
NBFCs: the middle path
Pros: more flexible on score and employer type, and usually faster than banks.
Cons: higher rates and fees than banks. Some still decline recent defaults.
Apply here if: your score is roughly 650 to 700, or you work for a smaller company.
Private lending partners: for low scores and past defaults
Pros: they consider applicants banks turn away, looking at current salary, job stability and existing EMIs. Someone usually reviews your case personally.
Cons: the highest cost, usually smaller amounts, and you must check the lender's credibility carefully.
Apply here if: your score is below about 650, or you have a settled or written-off account, but your salary is stable.
How to check that a lender is genuine
- The company's registered name, CIN and office address are clearly shown.
- You receive a written agreement showing the interest rate, all fees and the total repayment.
- No fee is collected before the loan is approved.
- The money is paid directly into your bank account.
- There is a clear grievance contact.
Read more about your rights in our summary of the RBI digital lending guidelines.
Where Indifunds fits
Indifunds is a loan facilitator based in Sector 51, Noida (a unit of Devdhan Narayana Finserv Pvt Ltd). We help salaried applicants in Delhi NCR, usually with an in-hand salary of ₹35,000 or more, find a suitable option among our lending partners, including when the CIBIL score is low or a bank has already said no. We do not collect any fee before approval, and all charges are explained before disbursal. Approval depends on eligibility and the lender's final decision.
See the personal loan in Delhi NCR page or check eligibility on the personal loan for low CIBIL score page.
Frequently asked questions
Is an NBFC loan safe?
NBFCs registered with the RBI are regulated lenders. Check the lender's name in the loan agreement and make sure all charges are disclosed.
Why are private lenders more expensive?
They take on more risk by lending to people with low scores or past defaults, so they price that risk into the rate.
Should I take the first offer I get?
No. Compare the total repayment amount, fees and prepayment terms. Use the EMI calculator to check affordability.
Can I move to a bank loan later?
Yes. After 12 to 24 months of on-time payments, your score may improve enough to refinance with a bank at a lower rate.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.