In this guide
Updated: 30 October 2026
Most loan rejections are not random. Lenders follow a checklist, and if you know it, you can fix many problems before you apply. This guide gives practical steps salaried people with a low CIBIL score can take in the next few weeks to improve their chances of approval.
Quick answer: To improve your approval chances with a low CIBIL score, clear any overdue amount, reduce your existing EMIs and card usage, correct errors in your credit report, make sure your salary is credited to your bank account, keep documents consistent, apply for a realistic amount and apply to only one suitable lender at a time.
What lenders look at, in order
- Identity and location: valid KYC and an address in the lender's service area.
- Income: salary amount and how regularly it reaches your bank account.
- Existing obligations: how much of your salary already goes to EMIs and card dues.
- Credit history: current overdues, past defaults, settlements and recent enquiries.
- Job stability: employer and time in the current job.
10 steps to improve your approval chances
1. Clear anything that is overdue today
A loan or card that is overdue right now is the biggest red flag. Paying it, even if your score does not change immediately, shows lenders the problem is under control.
2. Reduce your existing EMIs
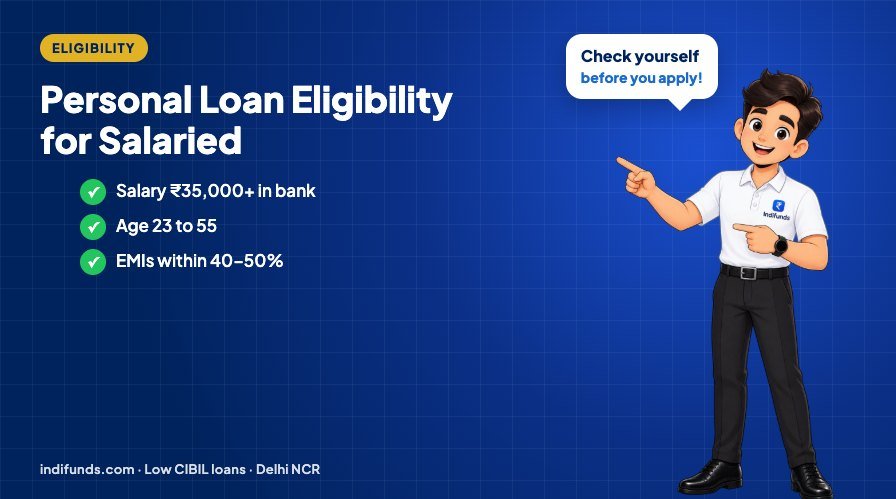
Close small app loans and bring card balances down. Lenders prefer your total EMIs within about 40 to 50% of your in-hand salary.
3. Lower your credit card usage
Using most of your card limit every month hurts your score. Try to keep the balance well below the limit before applying.
4. Check and correct your credit report
Look for closed loans showing as active, wrong amounts or loans that are not yours. Raise a dispute with the bureau. See how to check your CIBIL score for free.
5. Get your salary into one bank account
A clear six-month record of salary credits is often more important than the score for low-score applicants.
6. Keep documents consistent
Your name, date of birth, address and employer should match across PAN, Aadhaar, salary slips and bank statement.
7. Apply for a realistic amount
Asking for much more than your salary supports leads to rejection. Use the EMI calculator to pick an EMI you can carry.
8. Choose the right lender
Big banks often reject low scores automatically. NBFCs and lending partners that assess low scores are a better match. See NBFC vs private financer vs bank.
9. Apply to one lender at a time
Many applications in a short time lower your score and make you look desperate for credit.
10. Be honest about your past
Lenders will see your report. A short, honest explanation of a past problem, with proof that things are stable now, works better than hiding it.
A 30-day plan before you apply
| Week | What to do |
|---|---|
| Week 1 | Download your credit report; list every loan and card with dues |
| Week 2 | Pay overdue amounts; raise disputes for errors |
| Week 3 | Close small app loans; reduce card balances |
| Week 4 | Collect documents; calculate a realistic amount; apply to one lender |
Apply with Indifunds
Indifunds is a loan facilitator in Noida that works with lending partners. Salaried applicants in Delhi NCR with an in-hand salary of ₹35,000 or more, including those with a low CIBIL score or a past rejection, can check personal loan options from ₹50,000, payday loans from ₹5,000 and salary-advance loans up to ₹1 lakh. No fee before approval. Approval, amount and rate depend on eligibility, verification and the lender's final decision. Start on the low CIBIL personal loan page or read personal loan eligibility for salaried in Delhi NCR.
Frequently asked questions
How quickly can I improve my loan approval chances?
Clearing overdues, closing small loans and fixing report errors can help within a few weeks. A real score improvement usually takes months of on-time payments.
Does a higher salary guarantee approval?
No. A good salary helps, but high existing EMIs, recent missed payments or many recent enquiries can still lead to rejection.
Should I add a co-applicant?
A co-applicant with a good score and income can help, but they become equally responsible for repayment.
How long should I wait after a rejection?
Fix the likely reason first. Many borrowers wait a few weeks to a few months before applying again, and apply to only one suitable lender.
Will closing my credit card help?
Paying down the balance helps more than closing the card. Closing an old card can reduce your total limit and raise your usage ratio.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.