In this guide
Updated: 29 October 2026
Salaried people today get offers for a salary overdraft from their bank, a personal loan from lenders, and a "credit line" inside loan apps. They sound similar, but they work very differently, and the wrong choice can cost you a lot. This guide explains each in simple language, especially for people with a low CIBIL score.
Quick answer: A salary overdraft lets you spend a little more than your balance in your salary account and you pay interest only on what you use. A personal loan gives a lump sum with fixed EMIs. A credit line gives an approved limit you can draw from again and again. For a one-time need, a personal loan is the simplest and easiest to control. For small, repeated short gaps, an overdraft or credit line can work, but only if you repay quickly.
The three options compared
| Salary overdraft | Personal loan | Credit line | |
|---|---|---|---|
| Who offers it | Usually your salary-account bank | Banks, NBFCs | Banks, NBFCs, often through apps |
| How you get money | Spend beyond your balance | Lump sum once | Draw any amount up to the limit |
| Interest | Only on amount used, for days used | On the full loan for the tenure | Only on amount drawn |
| Repayment | Salary credit adjusts it | Fixed EMIs | EMIs for each draw or flexible |
| Limit | Often linked to salary | Based on income and profile | Based on profile; can change |
| With a low CIBIL score | Hard to get | Possible with some lenders | Some apps offer; check carefully |
| Main risk | Staying in overdraft every month | Taking a bigger loan than needed | Drawing again and again |
Salary overdraft
Some banks let salaried customers go into a small negative balance. Interest is charged daily on the overdrawn amount. It is handy for a few days' gap, but if your account is in overdraft every month, you are effectively living on borrowed money. Banks usually offer this only to customers with a good relationship and score.
Personal loan
You get the full amount once and repay it in fixed EMIs. It is the easiest to plan: you know the EMI and the end date from day one. For a single big expense, or to clear several smaller costly dues, it is usually the cleanest choice. See the complete personal loan guide.
Credit line
A credit line gives you an approved limit. You draw what you need, repay, and can draw again. Interest is charged only on what you use. It can be useful, but the easy re-draw makes it easy to stay in debt. Check that the credit line is from a bank or RBI-registered NBFC and read the fees for each draw. See safe vs fake loan apps.
Which one should you choose?
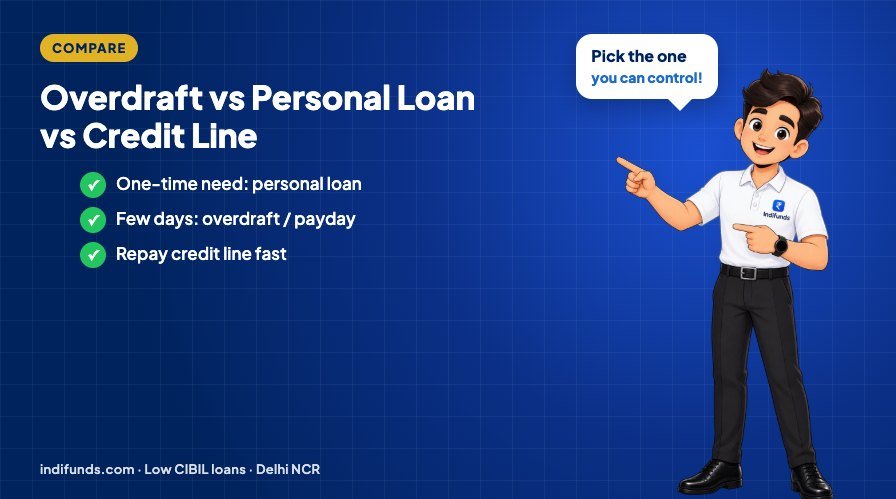
- One-time need (₹50,000 or more): personal loan with a fixed EMI.
- A few days until salary: overdraft if your bank offers it, or a short payday loan.
- Small repeated gaps: a credit line can work, but set a rule to repay each draw within the month.
- Low CIBIL score: a personal loan or a salary-advance loan from a regulated lender is usually the realistic option.
Indifunds helps salaried people in Delhi NCR, including those with a low CIBIL score, check payday, salary-advance and personal loan options with lending partners. No fee before approval; approval, amount and rate depend on eligibility, verification and the lender's final decision.
Frequently asked questions
Is a salary overdraft cheaper than a personal loan?
For a few days, it can be, because you pay interest only for the days and amount used. For months, a personal loan with a fixed EMI is usually cheaper and easier to control.
Does a credit line affect my CIBIL score?
Yes. It is reported like other credit. Using most of the limit or paying late lowers your score; paying on time helps.
Can I get a salary overdraft with a low CIBIL score?
It is difficult, because banks usually offer it to customers with a good record. A payday or salary-advance loan from a regulated lender is more realistic.
What is better for an emergency?
For a one-time emergency, a loan with a clear amount and end date is easier to manage. Read emergency loan options for a low CIBIL score.
Can I have a personal loan and a credit line at the same time?
Yes, but lenders count both when they check how much of your salary goes to repayments. Too many open lines can reduce your chances of future loans.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.