In this guide
Updated: 27 October 2026
Got a bonus, sold something or got a better job? Closing your personal loan early can save a lot of interest. But many borrowers do not know whether the lender can charge a penalty, what papers to collect, or how early closure affects the CIBIL score. This guide explains foreclosure and part-payment in simple words, along with the RBI rules that apply from 2026.
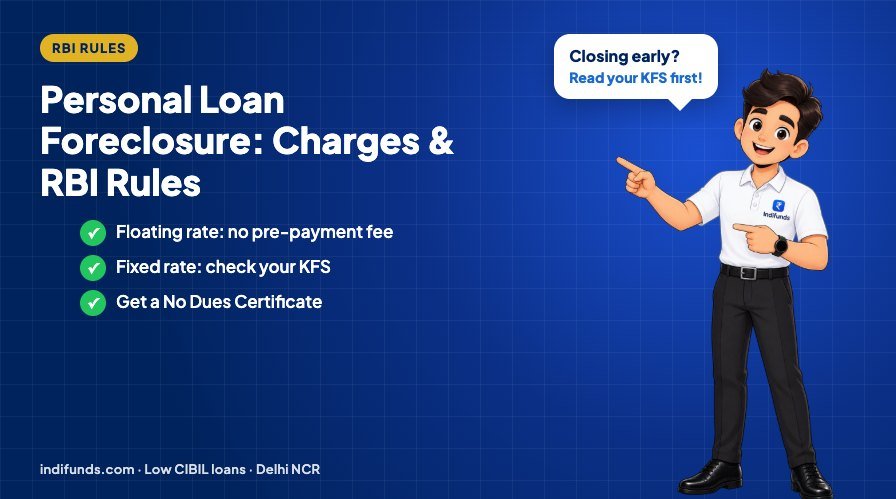
Quick answer: Foreclosure means paying off the whole loan before the tenure ends. Under RBI's pre-payment directions, banks and NBFCs cannot charge any pre-payment fee on floating-rate loans taken by individuals for non-business purposes (for loans sanctioned or renewed from 1 January 2026). Most personal loans are fixed-rate, and for those the lender may charge a foreclosure fee, but it must be disclosed upfront in your Key Fact Statement and loan agreement. Always collect a No Dues Certificate after closing.
Foreclosure vs part-payment
| Foreclosure | Part-payment (prepayment) | |
|---|---|---|
| What it means | You repay the full outstanding and close the loan | You pay a lump sum, the loan continues |
| Effect | No more EMIs | Lower EMI or shorter tenure |
| Typical lock-in | Many lenders allow it only after a few EMIs | Some lenders limit how often you can do it |
| Charges | As per your loan agreement (see RBI rules below) | As per your loan agreement |
What RBI rules say about pre-payment charges
- Floating-rate loans to individuals (non-business): no pre-payment or foreclosure charge, for loans sanctioned or renewed on or after 1 January 2026 under the RBI's pre-payment charges directions.
- Fixed-rate personal loans: a charge may apply, but it must be clearly disclosed in the Key Fact Statement and loan agreement. Lenders cannot add charges that were not disclosed.
Read your sanction letter or Key Fact Statement to see whether your loan is fixed or floating and what the foreclosure fee is. If something is unclear, ask the lender in writing. More on the rules in RBI digital lending guidelines explained.
Should you close your loan early?
Closing early saves the interest of the remaining months. The saving is biggest in the first part of the tenure, because more of each EMI goes to interest then. Close early if:
- The interest saved is more than the foreclosure fee.
- You still keep an emergency fund after paying.
- You do not have a costlier loan (like a credit card or app loan) that should be paid first.
If you have several loans, pay off the most expensive one first. Use the EMI calculator to compare.
How to foreclose a personal loan: step by step
Step 1: Ask for the foreclosure statement
Request the exact amount to close the loan on a given date, including any fee and GST.
Step 2: Pay only to the lender's official account
Pay through the lender's app, website or branch. Never pay a "settlement agent" in cash or to a personal UPI ID.
Step 3: Collect the No Dues Certificate
This letter proves the loan is fully closed. Keep it safely.
Step 4: Check your credit report after 30 to 45 days
The loan should show as "Closed", not "Settled". If it is wrong, raise a dispute with the credit bureau and the lender.
Foreclosure, settlement and your CIBIL score
Foreclosing a loan by paying the full amount is positive: the account shows as closed. A settlement, where you pay less than what you owe, shows as "Settled" and hurts your score for years. If you are struggling to pay, read loan settlement vs loan default before agreeing to settle.
Frequently asked questions
Is there any charge for closing a personal loan early?
For floating-rate loans to individuals for non-business use, RBI rules do not allow pre-payment charges on loans sanctioned or renewed from 1 January 2026. Most personal loans are fixed-rate, where a disclosed foreclosure fee may apply.
Does closing a loan early improve the CIBIL score?
It shows the loan as fully closed, which is good. The bigger benefit comes from paying all EMIs on time until then. The score does not jump just because you closed early.
Can I foreclose a loan in the first few months?
Many lenders allow foreclosure only after a minimum number of EMIs. Check the lock-in period in your loan agreement.
What documents should I get after closing a loan?
A No Dues Certificate and, for secured loans, the release of any security or documents you gave.
Is part-payment better than foreclosure?
If you cannot close the whole loan, a part-payment still reduces interest. Ask the lender whether it will reduce your EMI or the tenure; reducing tenure usually saves more interest.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.