In this guide
Your CIBIL score is the first number a lender looks at, so it makes sense to know it before you apply for any loan. Many people search for "civil check" or "cibil check" and land on paid services, but you can see your score and full credit report for free. This guide shows how, explains what the number means and what to do if you find a mistake.
Quick answer: Go to the official CIBIL website, choose the free annual credit report, enter your PAN, name, date of birth and mobile number, verify with the OTP and answer a few identity questions. You get your score and full report at no cost. Checking your own score never lowers it.
Your right to a free credit report
Under RBI rules, every credit bureau in India must give you one free full credit report every year. There are four bureaus: TransUnion CIBIL, Experian, Equifax and CRIF High Mark. Lenders may check any of them, so it is worth seeing at least your CIBIL report once a year and before every important loan application.
Step-by-step: check your CIBIL score for free
- Open the official CIBIL website (cibil.com) and select the option for your free annual CIBIL score and report.
- Create an account with your email address and a password.
- Enter your full name as on PAN, date of birth, PAN number, address and mobile number.
- Verify your mobile number with the OTP.
- Answer the identity questions about your existing loans or cards, if asked.
- Your score and report open on the dashboard. Download the report as a PDF for your records.
Paid plans are optional. The free yearly report already shows your score, every loan and card, payment history and enquiries.
What your score means
| CIBIL score | What lenders think | Usual result |
|---|---|---|
| 750 and above | Low risk | Banks approve easily, best interest rates |
| 700 to 749 | Good | Most lenders approve |
| 650 to 699 | Fair | Some banks, most NBFCs |
| 550 to 649 | High risk | Banks rarely; NBFCs and private partners case by case |
| Below 550 | Very high risk | Small or secured loans, based on income |
| NA or NH | No credit history | Treated as new to credit, not as bad |
For details on each band, read minimum CIBIL score for a personal loan and personal loan with a CIBIL score of 550 to 650.
What to check in your report
- Personal details: name spelling, date of birth, PAN and addresses.
- Accounts: every loan and card should be yours. Closed loans should show as closed.
- Payment history (DPD): the number of days a payment was late each month.
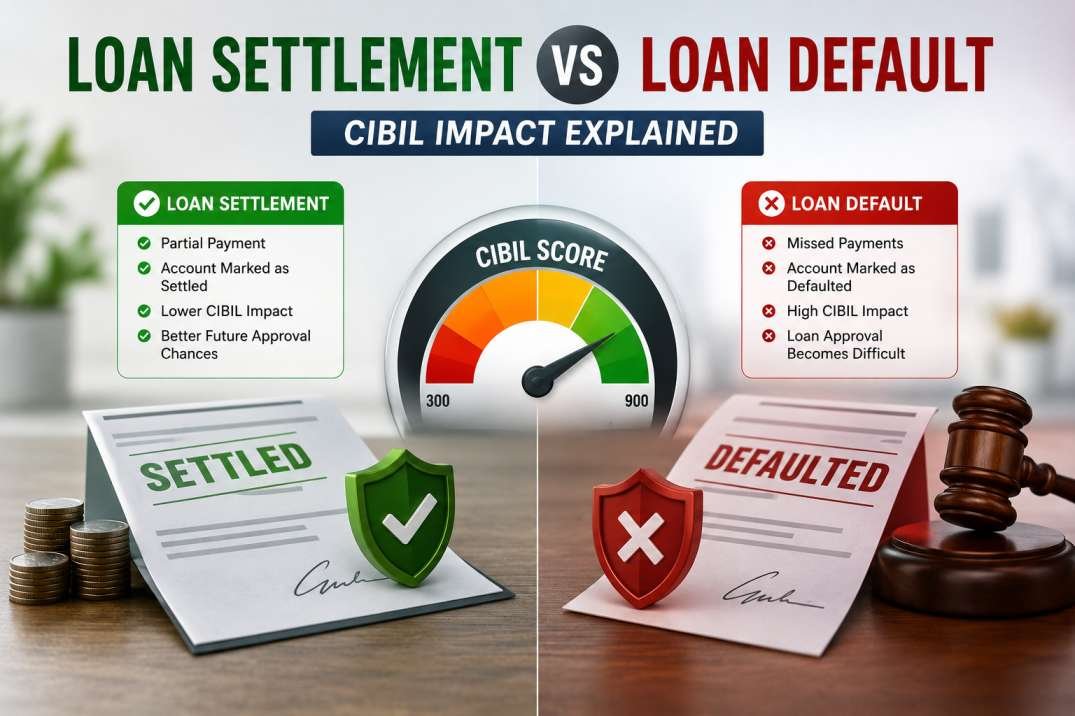
- Status words: "Settled" and "Written off" hurt your score more than late payments.
- Enquiries: loan or card applications made in your name.
Found an error? How to fix it
- Note the account and the wrong entry.
- Raise a dispute on the CIBIL website from your account, with proof such as a closure letter or payment receipt.
- CIBIL checks with the lender; the process usually takes about 30 days.
- If the lender does not respond, write to the lender's grievance officer and keep copies.
Low score? Your next steps
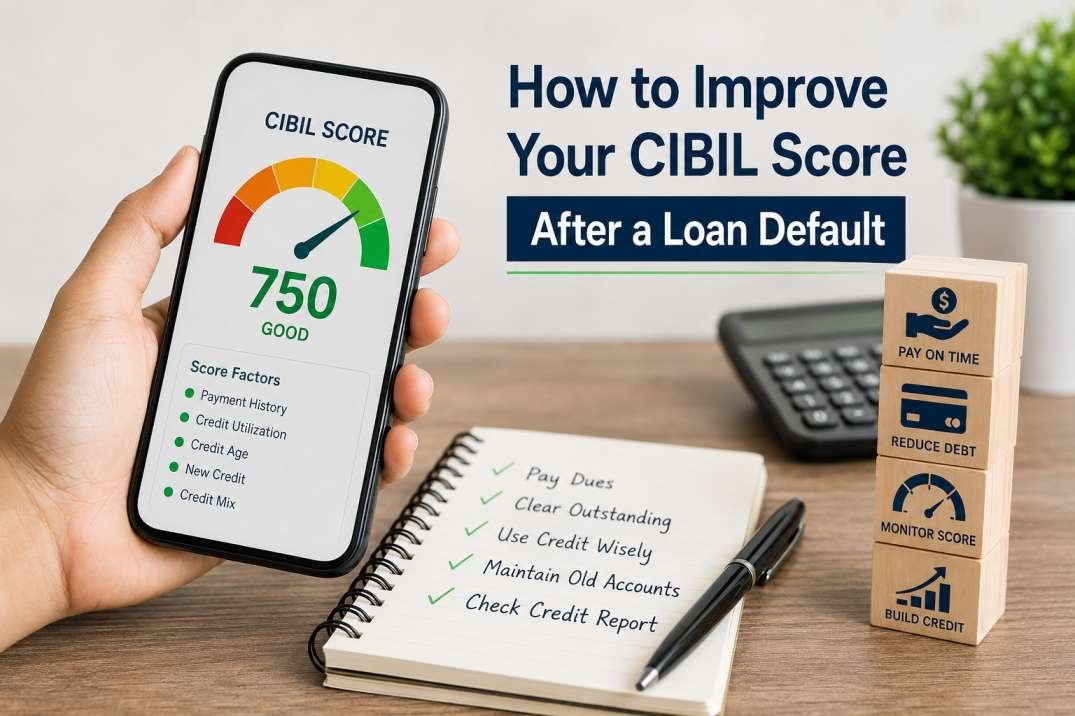
A low score is not the end. You can work on it with steps to improve your CIBIL score after a default, and if you need a loan now, read how to get a personal loan with a low CIBIL score. Indifunds helps salaried and self-employed borrowers in Delhi NCR with low CIBIL scores find suitable lenders; it is free to apply.
Frequently asked questions
Does checking my own CIBIL score reduce it?
No. Checking your own score is a soft enquiry and has no effect on the score. Only loan or card applications made to lenders are hard enquiries.
Can I check my CIBIL score with only my PAN card?
Your PAN is the main identifier, but you will also need your name, date of birth, mobile number and a one-time password to verify your identity.
How often is my CIBIL score updated?
Lenders report data to credit bureaus regularly, usually every month, so your score can change from month to month.
Is a CIBIL score and a credit score the same?
CIBIL is one of India's credit bureaus. Experian, Equifax and CRIF High Mark also give credit scores. Each bureau's score can be slightly different.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.