In this guide
A CIBIL score between 550 and 650 sits in a grey zone. Most large banks will decline you, but you are not out of options. Many salaried people in this range still get a personal loan from NBFCs or private lending partners, as long as their income is stable and their existing EMIs are under control. This guide explains what lenders look at in this score band and how to improve your chances.
Quick answer: With a CIBIL score of 550 to 650, banks usually decline, but NBFCs and private lending partners may approve a smaller personal loan at a higher rate if you have a regular salary, low existing EMIs and no very recent defaults. Apply to one suitable lender at a time and never pay any fee before approval.
What a score of 550 to 650 tells a lender
Lenders read your score together with the details behind it. A score in this range usually means one or more of the following happened in the last few years:
- A few EMIs or credit card payments were paid late.
- A loan or card was settled for less than the full amount.
- Credit card usage was very high for many months.
- Several loan applications were made in a short time.
The age of the problem matters. A late payment from three years ago, followed by a clean record, is viewed very differently from a default six months ago.
Which lenders consider this score range?
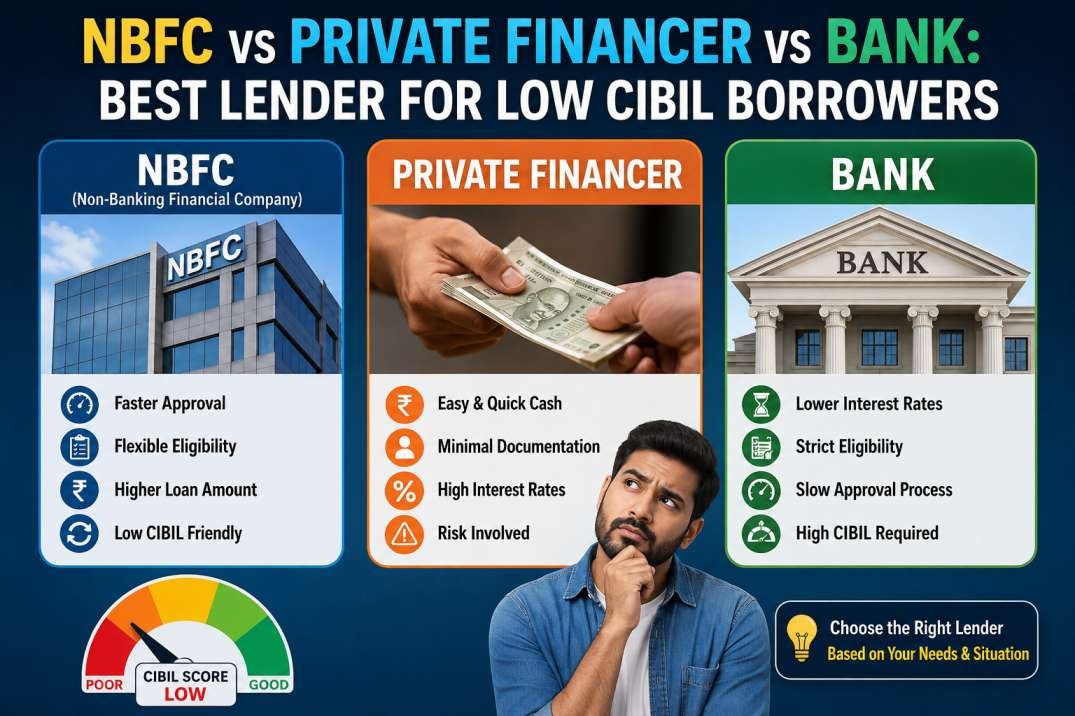
| Score | Banks | NBFCs | Private lending partners |
|---|---|---|---|
| 600 to 650 | Rarely | Often, case by case | Yes, case by case |
| 550 to 599 | Very rarely | Sometimes | Yes, based on income |
For a full comparison, read NBFC vs private financer vs bank.
Five factors that matter more than the score
1. A salary credited to your bank account
Regular monthly credits are the strongest proof that you can repay.
2. Your existing EMIs
Lenders want your total EMIs, including the new one, to stay within an affordable share of your salary.
3. Job stability
Six months or more with your current employer helps.
4. How recent the default is
A clean record in the last 6 to 12 months improves your profile.
5. Honesty about your history
A clear explanation of what went wrong and what has changed helps a manual reviewer.
What loan amount and cost to expect
In this score band, offers are usually smaller than what a bank would give and the interest rate is higher. Always ask for the total repayment amount in writing and compare it using the EMI calculator. Do not borrow more than you need.
How to apply step by step
- Download your credit report and note every negative entry.
- Dispute any entry that is wrong.
- Keep 3 months' salary slips and a 6-month bank statement ready.
- Check your eligibility with one lender that assesses low CIBIL profiles.
- Read the agreement fully before signing.
Indifunds, a Noida-based loan facilitator, helps salaried applicants in Delhi NCR with scores in this range through its lending partners. Start on the personal loan for low CIBIL score page.
Frequently asked questions
Can I get a personal loan with a CIBIL score of 600?
Yes, it is possible with NBFCs and private lending partners if your income is stable and existing EMIs are manageable.
Is 550 too low for a personal loan?
It is low for banks, but some lenders assess salaried applicants mainly on current income and repayment capacity.
Will a co-applicant help?
Yes. A co-applicant with a good score and income can strengthen your application.
How long until my score crosses 700?
With on-time payments and low card usage, many people see steady improvement over 12 to 24 months. Read how to improve your CIBIL score.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.