In this guide
- What is a salary advance loan?
- Can you get a salary advance with a low CIBIL score?
- What lenders look at besides your CIBIL score
- Eligibility checklist at a glance
- Documents to keep ready
- How to apply with Indifunds
- Mistakes that make a low-CIBIL application harder
- Is a salary advance the right choice for you?
- How a salary advance can help your score over time
- Frequently asked questions
- Check your eligibility
Updated: 6 November 2026
Your salary is fixed, but some expenses are not. A hospital bill, a rent deposit, a school fee or a family emergency can arrive ten days before payday. If your CIBIL score is low because of an old missed EMI, a settled credit card or a loan you could not close on time, a bank may say no quickly. A salary advance loan is one option many salaried people in Delhi NCR look at in this situation. This guide explains how it works with a low CIBIL score, what lenders look at besides the score, the documents to keep ready and the mistakes to avoid.
Quick answer: A salary advance loan is a short-term loan for salaried employees, given against their regular monthly income. With a low CIBIL score you can still apply, because lenders also look at your current salary, your job stability and your ability to repay. At Indifunds, a salary advance loan of ₹30,000 to ₹1 lakh* can be explored by salaried employees in Delhi NCR who earn ₹35,000 or more a month and are 23 to 55 years old. There is no fee before approval. Approval, amount, rate and tenure depend on eligibility, verification and the lender's final decision.
What is a salary advance loan?
A salary advance loan gives a salaried person money now against the income they will earn in the coming months. It is meant for short, genuine needs, not for long-term spending. You receive the amount in your bank account and repay it as agreed in the loan documents, usually in a short tenure linked to your salary cycle.
It is not the same as an advance from your employer. An employer advance comes out of your own future salary through HR. A salary advance loan comes from a lender, carries interest and charges, and is reported like any other loan.
Salary advance vs payday loan vs personal loan
| Point | Payday loan | Salary advance loan | Personal loan |
|---|---|---|---|
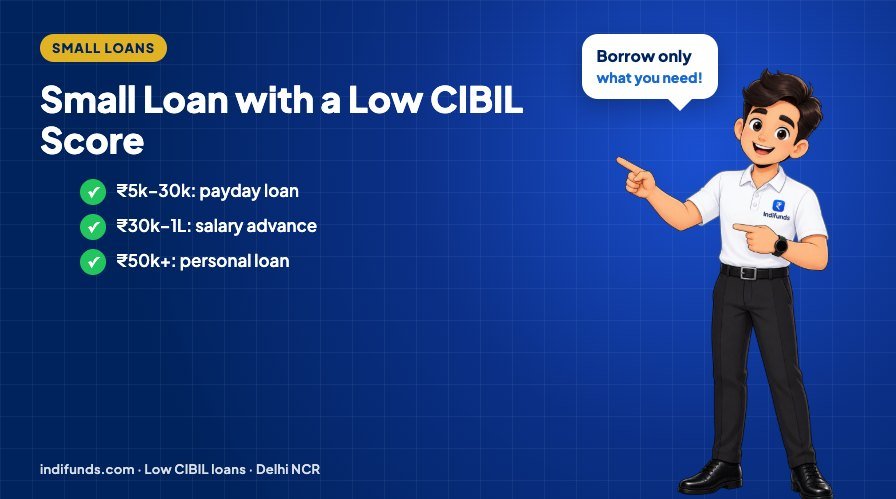
| Amount at Indifunds* | ₹5,000 – ₹2 lakh | ₹30,000 – ₹1 lakh | ₹50,000 – ₹10 lakh (higher amounts for strong profiles) |
| Typical use | Cash gap until the next salary day | Larger short-term need | Bigger planned or urgent expense |
| Repayment | In one go on salary day | Short, linked to salary | Monthly EMIs (6–36 months) |
| Pressure on next salary | High | Medium to high | Spread over months |
*Subject to eligibility and final approval. For a deeper comparison, read Payday Loan vs Salary Advance Loan: Which Is Right for You?
Can you get a salary advance with a low CIBIL score?
You can apply, and a low score does not automatically end your application. But be careful with any website or agent that says your score will not matter at all. Many people search for a "salary advance loan without CIBIL check", yet regulated lenders generally look at your credit history in some form. What changes for a salaried applicant is that the score is one part of the picture, not the whole picture.
A lender is mainly trying to answer one question: can this person repay this amount on time from their current income? A steady salary credited to your bank account every month is strong evidence for that, even if your past record has some marks on it.
What lenders look at besides your CIBIL score
1. Your monthly in-hand salary
Your net salary decides how much you can safely repay. At Indifunds the minimum monthly salary for this loan is ₹35,000. Your salary should be credited to your bank account, because the lender will check it in your bank statement.
2. Job stability
Lenders prefer applicants who work with a recognised organisation and have some work experience in their current job. Frequent job changes in a short time can make a lender cautious, because it is harder to judge future income.
3. Existing EMIs and repayment load
If a large part of your salary already goes into EMIs, a new loan becomes risky for you and for the lender. Before applying, add up all your current EMIs and card dues. If they already take a big share of your salary, a smaller amount or a different plan may be wiser.
4. The reason your score is low
A score that dropped because of one old default that is now cleared tells a different story from many recent missed payments. Lenders look at the pattern. If you have closed or settled old dues, keep the closure letters or NOC ready; they help explain your history.
5. Age and location
For this product at Indifunds you should be between 23 and 55 years of age and a resident of Delhi NCR, which includes Delhi, Noida, Greater Noida, Ghaziabad, Gurugram and Faridabad.
Eligibility checklist at a glance
| Criteria | What you need |
|---|---|
| Employment | Salaried employee with a recognised organisation |
| Monthly in-hand salary | ₹35,000 or more |
| Age | 23 to 55 years |
| Location | Resident of Delhi NCR |
| Loan amount | ₹30,000 to ₹1 lakh* |
| Fees before approval | None |
You can check where you stand in about two minutes with the free Indifunds eligibility checker.
Documents to keep ready
Exact documents depend on the lender and your profile, but having these ready usually saves time:
- PAN card and Aadhaar card (identity and address proof)
- Latest salary slips
- Bank statement of the account where your salary is credited
- Office ID card or employment proof
- Current address proof, if different from Aadhaar
- Closure letters or NOC for old loans you have cleared, if any
- An active mobile number linked to your documents
How to apply with Indifunds
- Apply online: fill the short form on the Instant Salary Advance Loan page. It takes about two minutes.
- Share your details: give your employment, income and other requested details.
- Verification: submit the documents needed for verification.
- Review the offer: if approved, read the amount, interest rate, charges, tenure and repayment dates carefully before you accept.
Submitting an application does not guarantee approval. All terms and charges are governed by the loan documents you sign.
Mistakes that make a low-CIBIL application harder
- Applying everywhere at once. Many loan applications in a short time can create several enquiries on your report and make lenders more careful. Apply where you are likely to be eligible.
- Asking for more than you need. A smaller amount that fits your salary is easier to approve and easier to repay.
- Hiding existing loans. Lenders can see them on your credit report. Being open about them builds trust.
- Paying an upfront "approval fee". Indifunds does not take any fee before approval. Anyone who asks you to pay before you get a loan is a red flag.
- Using unknown loan apps. Some apps charge very high costs and misuse phone data. Read the warning signs in our guide on the payday loan trap and how to escape it.
Is a salary advance the right choice for you?
A salary advance works best when the need is genuine, the amount is modest and you can repay it comfortably from the next few salaries. Ask yourself three questions before you apply:
- Will my salary still cover rent, groceries, school fees and existing EMIs after this repayment?
- Is this a one-time need, or will I need another advance next month?
- Would a personal loan with smaller monthly EMIs over a longer tenure be easier to manage?
If the need is bigger, or you know you will need several months to repay, compare the EMI of a personal loan first using the EMI calculator. Repeated short-term borrowing to cover the previous loan is a cycle worth avoiding.
For other quick options when money is needed at short notice, see our guide on an emergency loan with a low CIBIL score.
How a salary advance can help your score over time
A small loan repaid fully and on time adds a positive entry to your credit history. Over months, regular on-time payments, low card usage and no new defaults help a low score recover. Treat a salary advance as a short bridge, repay it on schedule and avoid taking a new loan just to close an old one.
Frequently asked questions
Can I get a salary advance loan with a CIBIL score below 650?
You can apply. Lenders also consider your current salary, job stability and existing EMIs, so a low score alone does not decide the result. Approval is not guaranteed and depends on verification and the lender's final decision.
Is there any salary advance loan without a CIBIL check?
Many people search for this, but you should not rely on such promises. Regulated lenders usually review your credit history. The better approach is to show steady income, low existing EMIs and a clear explanation of past issues.
How much salary advance can I get from Indifunds?
The salary advance loan range is ₹30,000 to ₹1 lakh for eligible salaried employees in Delhi NCR. The final amount depends on your salary, repayment capacity and the lender's assessment. If you only need cash until your next salary day and can repay it in one go, you can also look at a payday loan.
What is the minimum salary required?
The minimum monthly in-hand salary is ₹35,000, credited to your bank account. You should also be between 23 and 55 years of age.
Do I have to pay anything before approval?
No. Indifunds does not charge any fee before approval. If anyone asks you for money in advance to "process" or "guarantee" a loan, do not pay.
I live in Noida. Can I apply?
Yes. Salaried residents of Delhi NCR, including Noida, Greater Noida, Ghaziabad, Gurugram, Faridabad and Delhi, can apply. For help, call our support team on 8595702470.
Check your eligibility
If you are salaried in Delhi NCR and need a short-term amount despite a low CIBIL score, start with a free eligibility check. It takes about two minutes and there is no fee before approval. Apply for a salary advance loan on Indifunds and our team will assess your requirement.
*Loan approval, amount, interest rate and tenure are subject to eligibility criteria, verification and the lender's final approval. All terms and charges are governed by the loan documents.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.