In this guide
Updated: November 2026 – facts checked and related guides added.
It often starts with one small app loan to cover a few days. Then the repayment eats most of your next salary, so you take another loan, and then another. This is the payday loan trap, and it is very common among salaried people with a low CIBIL score. This guide explains how the cycle works and gives a practical plan to get out of it and stay out.
Quick answer: To escape the payday loan trap, list every short-term loan, stop taking new ones, talk to lenders about payment plans, and consider replacing several short loans with one personal loan that has an affordable monthly EMI. Then keep a small emergency fund so you do not need payday loans again.
How the payday loan trap works
- You borrow a small amount for a few days or weeks.
- Fees and interest make the repayment much larger than the amount you received.
- Repaying it in one go leaves too little for rent and bills.
- You take a new loan to fill the gap, often from another app.
- Late fees and penalties add up, and your CIBIL score falls.
Warning signs that you are in the trap
- You have loans from more than one app at the same time.
- You borrow to repay another loan.
- More than a third of your salary goes to short-term loan repayments.
- You receive recovery calls or threatening messages.
A step-by-step plan to get out
Step 1: Write down every loan
Note the lender, the amount due, the due date and all charges. Seeing the full picture is the first step to controlling it.
Step 2: Stop taking new short-term loans
Even a small new loan keeps the cycle running.
Step 3: Prioritise
Pay essentials first (rent, food, utilities), then the loans with the highest penalties.
Step 4: Talk to your lenders
Regulated lenders may agree to a payment plan. Ask for any agreement in writing.
Step 5: Consolidate into one EMI
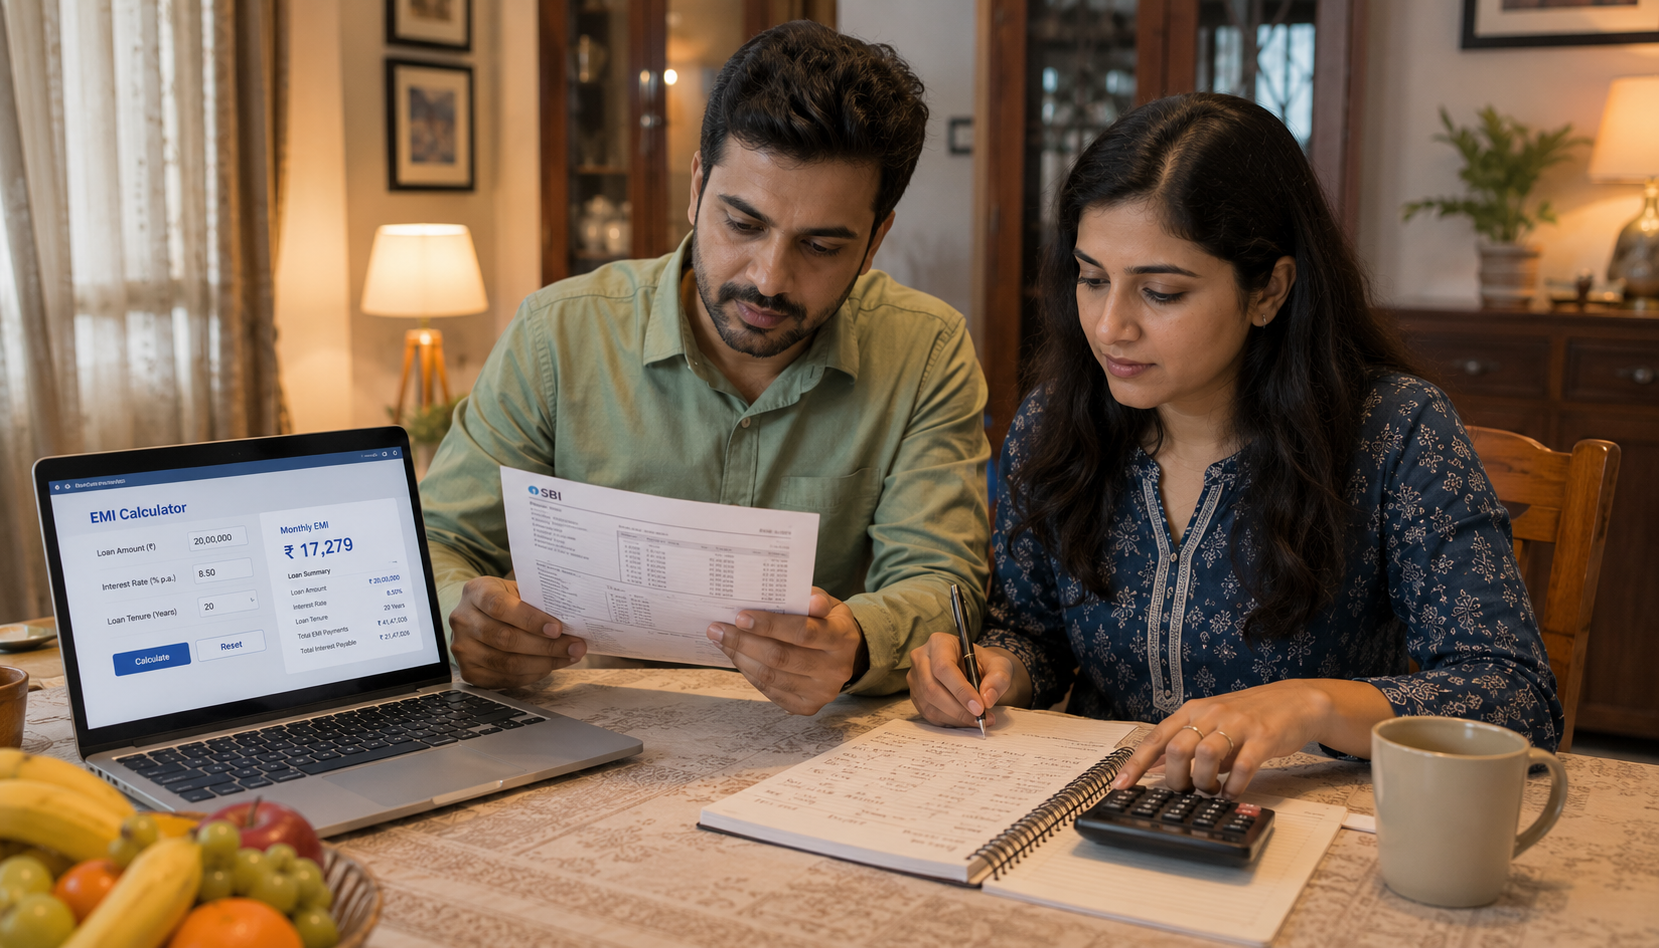
A personal loan with a 6 to 36 month tenure can replace several short loans with a single, predictable EMI. Check the EMI with the EMI calculator first. Compare costs in app loans vs a personal loan.
Step 6: Close and confirm
After repaying each app loan, get a closure confirmation and check that it appears on your credit report.
Your rights against harassment
RBI rules require lenders and their recovery agents to behave properly. They cannot threaten you, use abusive language or contact your friends and family to shame you. If this happens, complain to the lender's grievance officer, and if it is not resolved, to the RBI's complaint portal. Read our summary of the RBI digital lending rules.
How to stay out of the trap
- Build an emergency fund, starting with even ₹1,000 to ₹2,000 a month.
- Keep total EMIs within about 40% of your salary.
- Uninstall loan apps you no longer use.
- Rebuild your credit score with on-time payments. See how to improve your CIBIL score.
Need help consolidating?
Indifunds, a Noida-based loan facilitator, helps salaried applicants in Delhi NCR, including those with a low CIBIL score, apply for personal loans through its lending partners. No fee is collected before approval, and approval depends on eligibility and the lender's decision. Start on the personal loan for low CIBIL score page.
Related guides
- Payday loan: ₹5,000 to ₹2,00,000, apply online
- Payday loan vs salary advance loan
- Loan apps for CIBIL defaulters: safe vs fake
- Loan fee scam check: is this loan message real?
Frequently asked questions
Can I take a personal loan to repay payday loans?
Yes, if the new EMI is affordable and you stop taking new short-term loans. Otherwise you only add more debt.
Will repaying payday loans improve my CIBIL score?
Clearing overdue loans and paying on time from now on helps your score recover gradually.
What if a loan app harasses me?
Keep records of calls and messages, complain to the lender and, if needed, to the RBI complaint portal and the police cyber cell.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.