In this guide
Updated: 4 November 2026
Not all borrowing is bad. A loan that helps you earn more, avoid a bigger cost or keep your health can be a smart decision. A loan that pays for things you could have waited for, at a high rate, can quietly eat your salary for years. Knowing the difference between good debt and bad debt is one of the most useful money skills for any salaried person, and especially for anyone rebuilding a low CIBIL score.
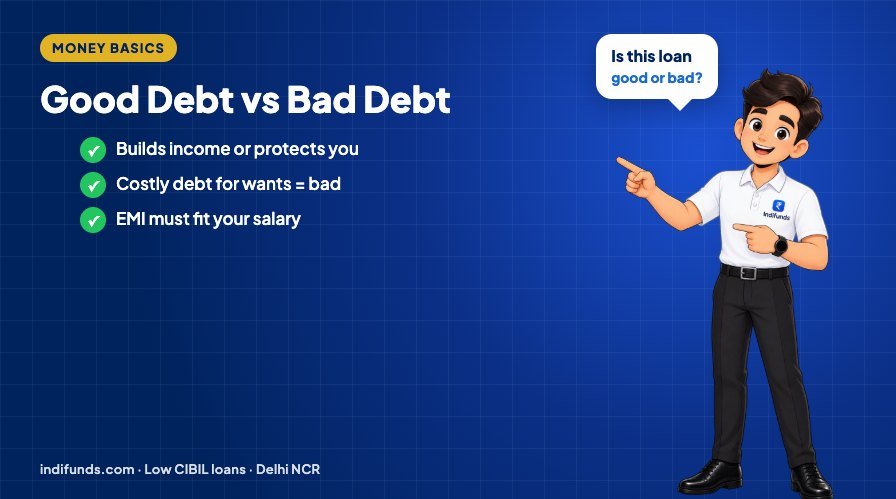
Quick answer: Good debt is borrowing at a sensible cost for something that improves your income, protects you from a bigger loss or builds a lasting asset, with an EMI you can comfortably repay. Bad debt is high-cost borrowing for things that lose value quickly or are not needed, or borrowing to repay other loans without a plan. The same loan can be good or bad depending on the purpose, the cost and whether you can afford it.
Good debt vs bad debt at a glance
| Usually good debt | Usually bad debt |
|---|---|
| Education or a course that raises your income | Shopping, gadgets and holidays on high-interest credit |
| A home loan you can afford | Credit card balances rolled over month after month |
| Medical treatment you cannot delay | Several small app loans running at once |
| One cheaper loan that replaces several costly ones | A new loan taken only to pay an old EMI |
| Tools or stock that help your business earn | Borrowing to invest in shares, crypto or betting |
Four questions that decide it
1. What does the money do for you?
If it raises your income, protects your health or job, or saves a bigger cost later, it leans towards good debt.
2. What does it cost?
Compare the total repayment, not only the EMI. Very high-cost credit turns even a useful purpose into a burden. Use the EMI calculator to see the total.
3. Can you repay it comfortably?
Keep all EMIs within about 40 to 50% of your in-hand salary. Use the EMI calculator.
4. Will it last longer than the loan?
Borrowing for 3 years to pay for something you will use for 3 months is usually a bad trade.
When good debt turns bad
- You miss EMIs, so penalties and a lower credit score follow
- You borrow more than the purpose really needs
- The tenure is stretched so long that the interest becomes huge
- You take more loans before the first one is under control
Getting out of bad debt
- List every loan and card with its balance, rate and EMI.
- Stop adding new high-cost debt.
- Pay the costliest debt first while paying the minimum on others.
- Consider replacing several costly debts with one EMI. See debt consolidation with a low CIBIL score.
- If you are stuck in short-term loans, read how to escape the payday loan trap.
How Indifunds can help
Indifunds is a loan facilitator in Noida that works with lending partners. If you are salaried in Delhi NCR with an in-hand salary of ₹35,000 or more and want to replace costly debt with one manageable EMI, our team can check your options, including with a low CIBIL score. No fee before approval; approval, amount and rate depend on eligibility, verification and the lender's final decision. Start on the low CIBIL personal loan page or read when you should take a personal loan.
Frequently asked questions
Is a personal loan good debt or bad debt?
It depends on the purpose, the cost and your ability to repay. A personal loan to replace costlier debt or pay for urgent treatment can be good debt; one for non-essential spending usually is not.
Is credit card debt always bad?
Using a card and paying the full bill on time is fine. Carrying a balance from month to month is expensive and usually bad debt.
Can bad debt affect my CIBIL score?
Yes. Missed payments, too many loans and high card use lower your score and make future loans harder.
Should I pay off bad debt before saving?
Keep a small emergency fund first, then put extra money towards the costliest debt. See how to build an emergency fund.
Is borrowing to invest good debt?
Usually not for individuals. Investment returns are uncertain, but EMIs must be paid every month.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.