In this guide
Your CIBIL report decides most loan applications before anyone speaks to you. Yet many borrowers never open it, or open it and do not understand the codes. This guide explains each important section in plain words, so you can spot problems, fix errors and know what a lender will see.
Quick answer: The key parts of a CIBIL report are your score, your account list with the payment history (DPD), the account status (Standard, Closed, Settled, Written off) and recent enquiries. Late payments shown as DPD, and Settled or Written-off statuses, lower your score the most. Check every entry and dispute anything that is wrong.
The main sections of a CIBIL report
| Section | What it shows |
|---|---|
| Score | A number from 300 to 900 summarising your credit behaviour |
| Personal information | Name, date of birth, PAN and addresses |
| Accounts | Every loan and credit card, with amounts and status |
| Payment history | Month-by-month record of on-time or late payments |
| Enquiries | Lenders who checked your report after you applied |
What DPD means
DPD stands for days past due: how many days late a payment was in a given month.
- 000 or STD: paid on time.
- 030, 060, 090: 30, 60 or 90 days late.
- SMA / SUB / DBT / LSS: increasingly serious overdue categories.
Even one 30-day delay can lower your score. Repeated 90+ DPD entries signal serious default.
Account status codes
Standard / Active
The account is running normally.
Closed
You repaid fully. This is the best status for a finished loan.
Settled
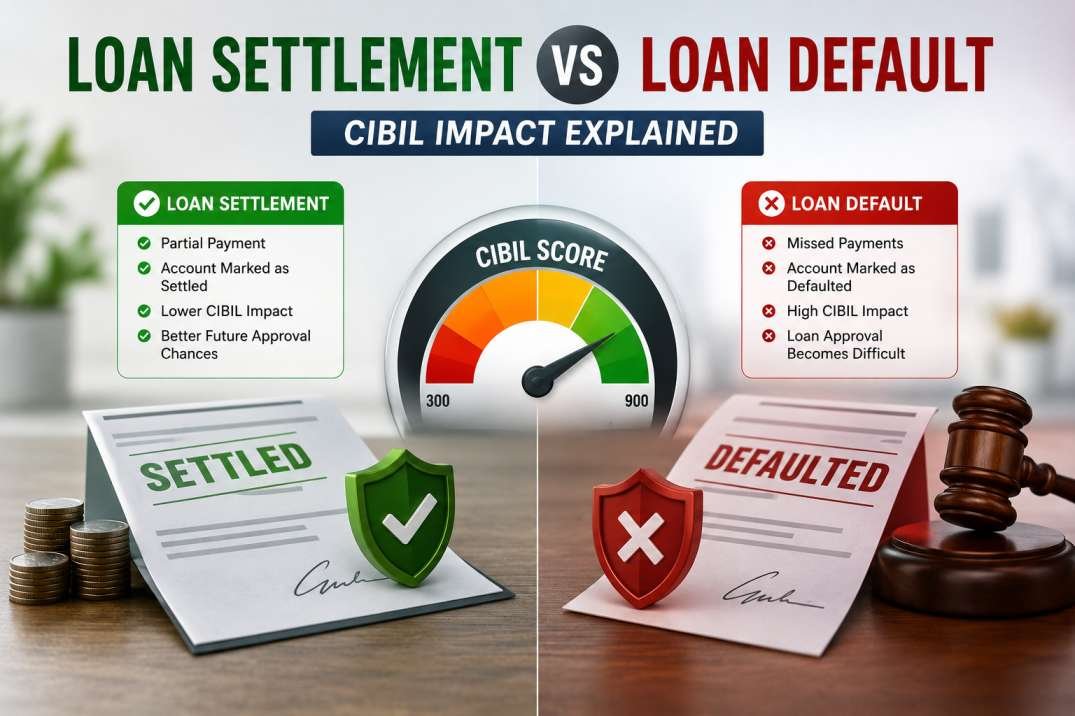
The lender accepted less than the full dues. Lenders see this as a negative sign. Learn more in loan settlement vs loan default.
Written off
The lender has recorded the dues as a loss. This is one of the most damaging statuses.
Enquiries: why too many hurt
Each time you formally apply for a loan or card, a hard enquiry is added. Many enquiries in a short period make you look urgently in need of credit. Checking your own report does not count.
How to spot and fix errors
- Check that all accounts belong to you.
- Look for loans you closed that still show as active.
- Check for late payments you know were made on time.
- Raise a dispute on the credit bureau's website with proof.
- Follow up with the lender until the record is corrected.
Using your report to get a loan
Once you understand your report, you can choose the right lender and explain your history honestly. If your report shows past problems but your salary is stable today, read how to get a personal loan with a low CIBIL score or check the personal loan for low CIBIL score page.
Frequently asked questions
How often should I check my CIBIL report?
At least once a year, and before any major loan application.
Does checking my report lower my score?
No. Checking your own report is a soft enquiry.
How long does a dispute take?
Usually about 30 days, depending on how quickly the lender responds.
Can a Written-off status be changed?
If you pay the full dues, ask the lender to update the status. Lenders decide this case by case.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.