In this guide
A low CIBIL score does not mean you can never get a personal loan in India. It means you need to apply in the right place, with the right documents, and with realistic expectations about the amount and interest rate. This step-by-step guide explains how salaried people with a low or damaged credit score can still borrow, and what to avoid along the way.
Quick answer: To get a personal loan with a low CIBIL score in India, check your credit report first, choose a lender that assesses low-score profiles (usually an NBFC or a private lending partner, not a large bank), show strong proof of current income, apply to one lender at a time and be honest about your past. Loans are usually smaller and costlier than bank loans, and no genuine lender asks for a fee before approval.
What counts as a low CIBIL score?
CIBIL scores range from 300 to 900. Here is how lenders generally see each range:
| CIBIL score | What it usually means for a personal loan |
|---|---|
| 750 to 900 | Strong profile. Banks compete for you with their best rates. |
| 700 to 749 | Good profile. Most banks and NBFCs will consider you. |
| 650 to 699 | Fair. Banks become selective; NBFCs remain an option. |
| 600 to 649 | Low. Most banks decline; some NBFCs and private lenders assess case by case. |
| Below 600 or a recent default | Very low. Mainly private lending partners or secured loans, based on income and repayment capacity. |
| No score (NH / -1) | New to credit. Some lenders treat this differently from a low score. |
For lender-wise cut-offs, read the minimum CIBIL score for a personal loan.
Why your CIBIL score is low
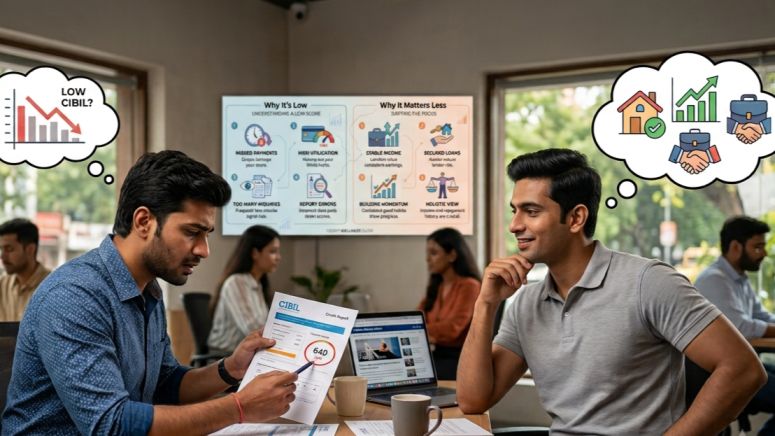
- Late or missed EMIs on loans or credit cards.
- Settled or written-off accounts, where the full dues were not paid.
- High credit card use, using most of your limit every month.
- Many loan enquiries in a short time.
- Errors in your report, such as a loan you closed still showing as active.
Your score reflects the past. Many lenders that work with low-score borrowers give more weight to what is true today: a steady salary, a stable job and an EMI you can afford.
Step-by-step: how to get a personal loan with a low CIBIL score
Step 1: Check your credit report before you apply
Download your report and read every account. Note overdue amounts, settlements and any entries that look wrong. Raise a dispute for errors, as a correction can lift your score.
Step 2: Pick the right type of lender
Applying to big banks with a low score usually ends in rejection and another hard enquiry. NBFCs and private lending partners are more likely to assess your full profile. Compare them in NBFC vs private financer vs bank.
Step 3: Prepare documents that prove your current income
Salary slips for the last 3 months, a 6-month bank statement showing regular salary credits, Aadhaar and PAN. Consistent salary credits matter more than anything else for a low-score application. See the full document checklist.
Step 4: Apply to one lender at a time
Each formal application adds a hard enquiry. Space out your applications and start with a lender whose criteria you actually meet.
Step 5: Be open about your past
Lenders will see your report anyway. A short, honest explanation (a job loss, a medical emergency, a settled card) and proof that your situation is stable now helps your case.
Step 6: Borrow only what you can repay
Use the EMI calculator to keep total EMIs within about 40 to 50% of your in-hand salary. A smaller loan that you repay on time rebuilds your score.
What low CIBIL borrowers should avoid
| Mistake | Why it makes things worse |
|---|---|
| Applying to many lenders in one week | Each hard enquiry lowers your score further. |
| Paying an "advance fee" to get approved | Genuine lenders never charge before approval. This is a common fraud. |
| Using several instant loan apps | High fees and very short tenures often lead to a debt cycle. |
| Hiding existing loans | The lender sees them in your report, and the application is rejected. |
| Borrowing more than you need | A high EMI raises the risk of another default. |
How Indifunds helps low CIBIL borrowers in Delhi NCR
Indifunds is a loan facilitator based in Noida that works with lending partners. If you are salaried in Delhi NCR, usually with an in-hand salary of ₹35,000 or more, our team reviews your application manually, looking at your salary, job stability, existing EMIs and the history behind your credit report.
- Loan amounts typically from ₹50,000 to ₹5 lakh, and up to ₹10 lakh for strong profiles.
- Tenure from 6 to 36 months.
- No fee collected before approval; all charges explained before disbursal.
- Money transferred directly to your bank account after the agreement is signed.
Approval, amount and interest rate depend on eligibility, verification and the lender's final decision. Check your eligibility on the personal loan for low CIBIL score page.
Frequently asked questions
Can I get a personal loan with a CIBIL score of 500?
It is difficult with banks, but some private lending partners assess scores in this range if you have a stable salary, salary credited to your bank account and manageable existing EMIs. Expect a smaller amount and a higher rate.
Can I get a personal loan with a CIBIL score of 600?
Yes, it is possible with some NBFCs and private lenders. Your income, job stability and existing EMIs will decide the amount and rate.
What is the minimum salary for a low CIBIL personal loan?
It varies by lender. For Indifunds in Delhi NCR, applicants usually need an in-hand salary of ₹35,000 or more.
How long does approval take?
After complete documents are submitted, verification and approval usually take a few working days, depending on your profile.
Will applying hurt my CIBIL score?
A formal application creates a hard enquiry, which can lower your score slightly. That is why you should apply to one suitable lender at a time.
What interest rate should I expect?
Rates for low CIBIL profiles are higher than bank rates and depend on the lender and your risk profile. Always compare the total repayment amount and read the loan agreement before signing.
Can a CIBIL defaulter get a home loan?
It is harder. Large secured loans usually need a better score or a strong co-applicant. Many people first rebuild their score with a smaller loan repaid on time. Read 5 real loan options for CIBIL defaulters.
Check your loan eligibility
Salaried in Delhi NCR? Low CIBIL score or a past rejection? Our team will assess your profile.
Takes about 2 minutes. No upfront charges.